Bitcoin day trading that goes home flat
Low Tide day-trades Bitcoin from Monday to Friday. At 01:00 server time it rests a buy stop above the day's opening price and a sell stop below it, each one 0.4 × yesterday's range away. Whichever side breaks first is the trade. Everything is closed out by 23:00, so it never pays overnight swap.
It is a simple idea run strictly. One position at a time, flat every night.
How it trades
A buy stop and a sell stop placed at 01:00, each 0.4 × yesterday's range either side of the open.
Stop loss 1 × yesterday's range. Take profit 2 ×.
At most one long and one short a day. One position open at a time.
Flat by 23:00 every day, so no overnight swap is ever paid.
No weekend trades, new in v4.09. Weekend breakouts lost money in every year they traded.
No grid. No martingale. A stop loss and a take profit on every order.
What the backtest shows
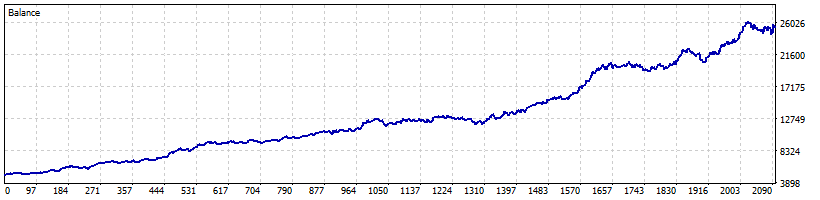
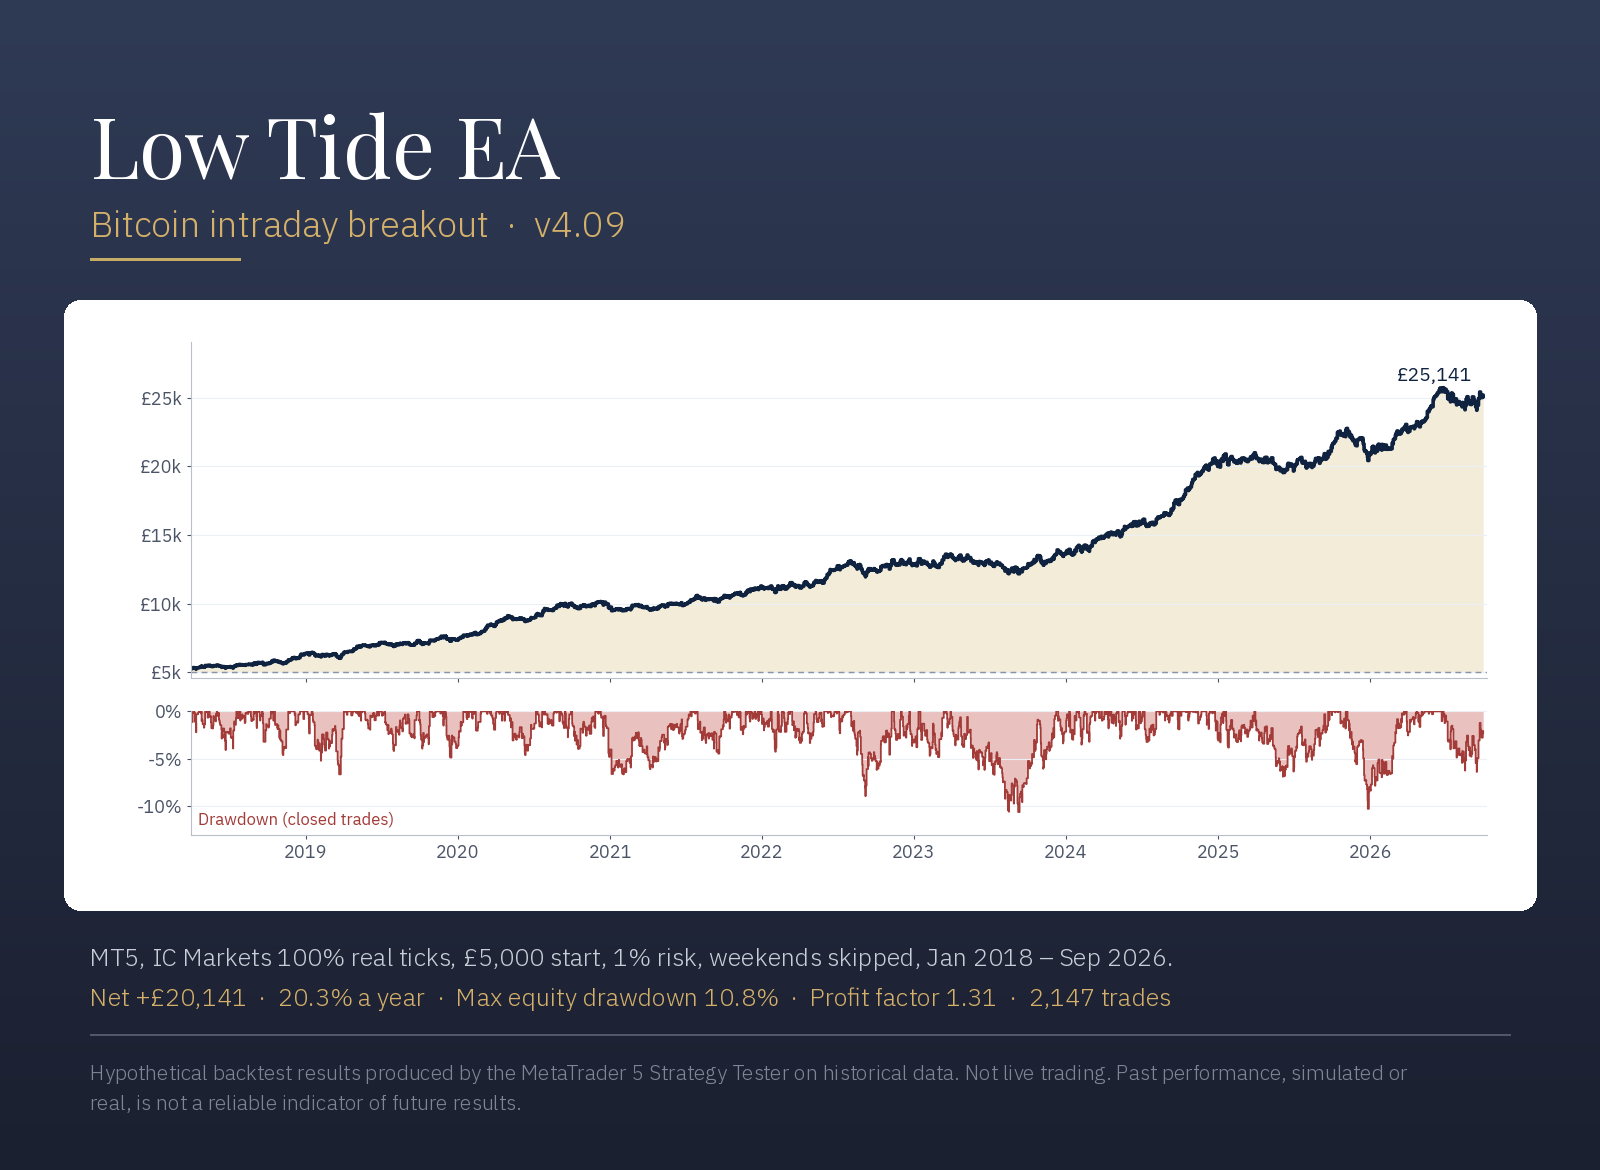
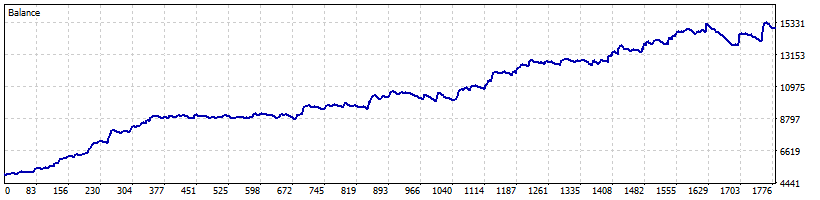
MT5 Strategy Tester on IC Markets data, 1 April 2018 to 30 September 2026, £5,000 start, 1.0% risk per trade, weekends skipped, 87% history quality, commission included.
Net profit: +£20,538 (£5,000 → £25,538)
Return: 21.2% a year
Max drawdown: 10.8% equity · 10.2% balance
Profit factor: 1.33
Trades: 2,087 · four or five a week
Win rate: 50.9%
Positive years: 9 out of 9
At the portfolio setting: 0.75% risk · 15.2% a year · 7.4% drawdown
Hypothetical results produced by the MetaTrader 5 Strategy Tester on historical data. Not live trading. Past performance, simulated or real, is not a reliable indicator of future results.
What to expect
About half the trades win. The average win is 1.3 times the average loss. Plenty of trades close at 23:00 rather than at the stop or the target, which is the system doing its job.
69% of months were positive in testing. The worst month was −7.1%. Every calendar year was positive, from +6% in 2025 to +46% in 2024. The longest losing run was 11 trades.
Because it enters with resting stop orders it fills at the breakout level. Costs still bite at this trade frequency, so a raw-spread account makes a real difference to the result.
What you need
MetaTrader 5, attached to a BTCUSD H1 chart.
A hedging or netting account. Server clock GMT+2 or GMT+3.
A raw-spread, low-commission account. This one is cost-sensitive.
A VPS is strongly advised, since the entries are time-based.
What you get
LowTide_v4.09.ex5
Two set files: one for running it on its own, one for the portfolio risk setting
The summary sheet and the full manual
Free updates, plus email support from me
Trading carries risk and you can lose money. Test on a demo account first. Only trade with money you can afford to lose.